What is the market overview and industry significance of the Circular Economy Consulting Services Market?
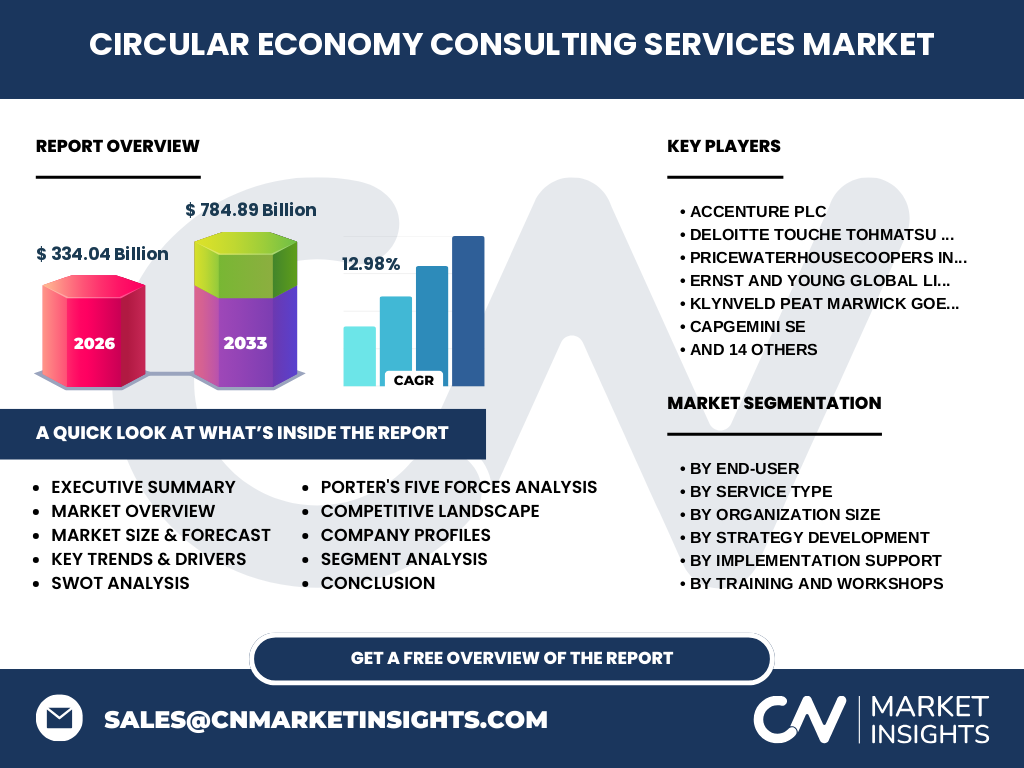
Our analysis indicates that the Circular Economy Consulting Services Market is valued at 334.04 Billion in 2026. This sector helps heavy industries transition away from linear 'take-make-waste' models by optimizing raw material usage, meeting stringent European Union and North American environmental mandates, and deploying proprietary lifecycle tracking methodologies across complex manufacturing value chains.
Structural Growth Drivers and Market Restraints
Based on our research, growth is propelled by escalating corporate ESG mandates and tightening regulatory penalties for scope 3 emissions. However, the Circular Economy Consulting Services Market faces severe restraints, notably high upfront advisory costs and a critical shortage of technical specialists capable of executing complex material flow analyses and reverse logistics infrastructure overhauls.
Emerging Trends Reshaping Advisory Paradigms
The market is witnessing a profound shift toward digital-first circularity, where firms integrate artificial intelligence with material recovery solutions. The Circular Economy Consulting Services Market industry trends highlight that clients increasingly demand predictive analytics for waste reduction processes and automated tracking of secondary raw materials to satisfy aggressive corporate net-zero timelines.
How did the COVID-19 pandemic impact the Circular Economy Consulting Services Market?
The pandemic initially disrupted advisory pipelines as enterprises prioritized short-term liquidity over long-term sustainability restructuring. Yet, the subsequent recovery triggered a resilient rebound in the Circular Economy Consulting Services Market, as governments tied post-pandemic stimulus packages directly to green transition frameworks and localized supply chain resilience.
Competitive Benchmarking and Market Concentration
The competitive landscape features a distinct oligopoly blending elite management consultancies like McKinsey And Company and The Boston Consulting Group Inc. with engineering specialists such as WSP Global Inc. and Arcadis N.V. The Circular Economy Consulting Services Market analysis shows tier-one players aggressively acquiring boutique sustainability firms to bolster specialized capabilities in reverse logistics and circular business model innovation.
Executive Summary of Key Findings
Our proprietary research establishes that the Circular Economy Consulting Services Market represents a vital frontier for industrial transformation. Driven by surging demand for supply chain integration and regulatory compliance, the sector is positioned to outpace traditional management consulting as corporations race to decouple financial growth from virgin resource extraction.
Market Forecast and Long-Term Growth Trajectory
The data suggests the Circular Economy Consulting Services Market will expand from 334.04 Billion in 2026 to reach 784.89 Billion by 2033, expanding at a robust 12.98% CAGR. This acceleration reflects mandatory corporate sustainability reporting and the scaling of circular industrial parks worldwide.
Segmentation Analysis across End-Users and Services
The Circular Economy Consulting Services Market is segmented by end-user into Manufacturing, Retail And Consumer Goods, Automotive, Energy And Utilities, Construction And Real Estate, and Other End-Users. Service delivery spans Strategy Development, Implementation Support, Assessment And Evaluation, and Training And Workshops, catering to Small, Medium, and Large Enterprises seeking tailored lifecycle interventions.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with Europe leading adoption due to aggressive European Union circular economy action plans. Meanwhile, North America demonstrates rapid acceleration driven by corporate voluntary commitments, and Asia-Pacific emerges as a high-growth frontier fueled by massive manufacturing hubs seeking resource optimization and waste reduction.
In-Depth Regional Review and Localization Challenges
European markets prioritize regulatory strategy and policy alignment, whereas North American engagements focus heavily on technology deployment for circular systems and reverse logistics setup. Regional growth in Asia-Pacific requires localized advisory models that navigate complex municipal waste frameworks and fragmented recycling supply chains across major industrial corridors.
Strategic Positioning of Leading Companies
Industry leaders deploy distinct strategic moats. Firms like Accenture plc and Capgemini SE leverage deep technology integration capabilities, while accounting giants such as Deloitte Touche Tohmatsu Limited and PricewaterhouseCoopers International Limited dominate circularity performance metrics development and ESG audit readiness for multinational corporations.
Porter's Five Forces Analysis
Supplier power remains moderate due to the proprietary nature of lifecycle impact analysis methodologies. However, buyer power is high, forcing consultancies to differentiate through specialized domain expertise in sectors like automotive and construction. Threat of substitution is low given the complex regulatory environment mandating certified expert validation.
SWOT Analysis of the Advisory Ecosystem
Strengths lie in deep multi-industry expertise and proprietary assessment tools. Weaknesses include high project delivery costs. Opportunities abound in emerging material recovery solutions and executive leadership training. Threats stem from economic volatility and potential dilution of advisory standards by non-certified greenwashing consultants.
Value Chain Analysis from Raw Materials to End-Users
The advisory value chain originates at the raw material sourcing stage, moving through manufacturing process redesign, supply chain integration, and ultimate end-of-life reverse logistics setup. Consultants intervene at critical nodes to ensure waste streams are successfully converted into secondary inputs, maximizing asset recovery value for clients.
Investment Insights and High-Potential Growth Areas
High-potential investment areas within the Circular Economy Consulting Services Market include digital tooling for material flow analysis and specialized training workshops for manufacturing executives. Investors should target consultancies possessing proprietary technology deployment frameworks that automate circular readiness assessments.
Conclusion and Strategic Takeaways
The Circular Economy Consulting Services Market is an essential catalyst for modern industrial sustainability. With market size projected to reach 784.89 Billion by 2033, early investments in specialized consulting capabilities will separate market leaders from legacy enterprises struggling with upcoming regulatory compliance.
Research Methodology and Baseline Triangulation
Our findings are derived from rigorous triangulation combining primary stakeholder interviews with C-suite sustainability executives, secondary analysis of global trade registry data, and macroeconomic ESG indicators. This multi-layered approach ensures precise market sizing and reliable long-term forecasting for the Circular Economy Consulting Services Market industry trends.
Scope of the Report and Analytical Limitations
This report covers global consulting deployments across manufacturing, retail, automotive, energy, and construction sectors. Limitations include rapid regulatory shifts in developing jurisdictions and proprietary confidentiality constraints among private consulting partnerships, which may obscure localized fee structures.
Recent Developments and Strategic Industry Moves
Recent strategic moves in the Circular Economy Consulting Services Market feature major consultancies forming targeted partnerships with specialized analytics platforms like Sphera Solutions Inc. and boutique circular innovators such as Closed Loop Partners LLC to enhance their technological edge in lifecycle impact analysis and supply chain traceability.